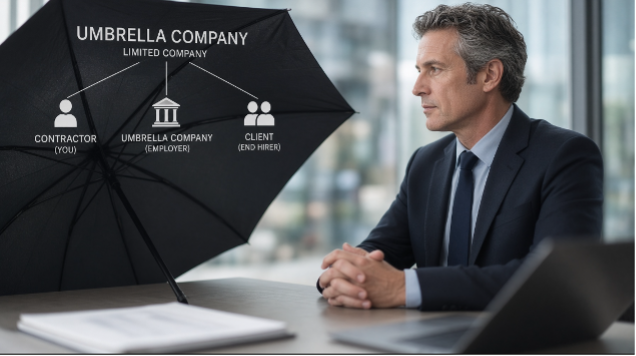

Readers considering moving to contract work using an umbrella company should be aware of new regulatory changes planned for 2027 may influence their decision. This guide explains how umbrella companies work and highlights the planned 2027 changes. An umbrella company can offer a way to take on contract work without setting up and running your own limited company, particularly if you are new to contracting or planning a short assignment. But, before accepting a role, it is important to have a thorough understanding of how this structure works in so for as knowing: who employs you, how your pay is calculated and what the arrangement means for your rights.
In a typical umbrella arrangement, a recruitment agency finds the assignment, the client receives your services and the umbrella company employs you and pays your wages through PAYE. You are therefore an employee of the umbrella, rather than a self-employed supplier for that assignment.
You submit timesheets, the agency charges the client and pays the umbrella, and the umbrella processes your wages. The agency may ask you to use a preferred umbrella company, although you may be able to choose your own.
The main attraction is reduced administration: you do not need to establish a limited company for the assignment or take on its company-record and VAT-return responsibilities. That can suit someone testing contract work or taking a short-term role, but the umbrella charges a fee for its service.
Compare the full arrangement, not simply the advertised rate. Ask for a written explanation of the fee, expected gross salary, deductions and take-home pay before agreeing to proceed.
Your advertised rate is not your salary
The assignment rate is the amount paid to the umbrella company, not necessarily your gross pay. It funds costs including the umbrella’s margin, employer National Insurance, employer pension contributions and, where applicable, the Apprenticeship Levy, with holiday pay also accounted for in the calculation.
Once gross pay has been calculated, the umbrella deducts income tax, employee National Insurance, employee pension contributions, any applicable student loan repayments and other authorised or legally required deductions to arrive at take-home pay. Employer National Insurance and employer pension contributions must not be deducted from your gross salary as though they were employee contributions.
Your recruitment agency must provide a key information document identifying the umbrella, the minimum assignment rate, deductions and minimum gross pay. Ask for a reconciliation statement showing how the assignment rate becomes gross pay, alongside the payslip showing deductions from that salary.
Employment rights and holiday pay
Umbrella employees have employment rights, including paid holiday and payment of at least the applicable minimum wage, and must be automatically enrolled into a workplace pension if eligible. Check how holiday pay is calculated and paid, rather than assuming it will arrive separately when you take leave.
Read the employment contract alongside the assignment details. Ask what happens when the assignment ends and whether any pay is due between assignments.
IR35 concerns work supplied through a contractor’s own intermediary, usually a personal service company, and applies on a contract-by-contract basis. An assignment advertised as “inside IR35” may lead the client or agency to ask the contractor to work through an umbrella instead.
HMRC says the off-payroll working rules are unlikely to apply where the worker is employed by an umbrella company. That is different from treating an umbrella as a way to avoid employment taxes: its role is to employ the worker and operate PAYE.
For payments made from 6 April 2026, the recruitment agency contracting with the end client is responsible for ensuring the umbrella operates PAYE correctly; if there is no agency, that responsibility falls to the end client. HMRC can recover underpayments from that agency or client, while the umbrella remains responsible for calculating PAYE and paying HMRC on time.
For businesses using contractors, this means outsourcing payroll does not remove the need to check the supply chain. Ask your agency how it checks the umbrella’s PAYE compliance.
Employment regulation follows a separate timetable: the Fair Work Agency began operating on 7 April 2026, but its published guidance says it does not currently regulate umbrella companies directly. The government schedules umbrella-company regulation for 2027, with future dates subject to parliamentary processes and possible change.
Be cautious about promises of unusually high take-home pay: HMRC identifies purported non-taxable loans, payments exceeding the payslip amount and untaxed payments from another organisation as possible signs of tax avoidance. Keep your payslips and compare the deductions with your HMRC, pension and student loan records where relevant.
If pay or employment rights are unclear, raise the issue with the umbrella first, then seek help from Acas, Citizens Advice or your union if concerns remain.
For further information about pay, deductions and employment rights, see HMRC’s guidance on working through an umbrella company.
In Case You Missed It:

This guide is for general information only and does not constitute financial, tax or legal advice. Before deciding to work through an umbrella company, readers are recommended to seek advice from a qualified financial adviser or accountant with relevant experience of contractor arrangements, who can assess their individual circumstances, explain the costs and tax implications, and advise whether this route is appropriate for them.